

My Airtel analysis by Appwee
I use My Airtel as a practical everyday tool rather than as an app I open for entertainment. It brings several routine Airtel tasks into one place: recharging a mobile line, paying bills, transferring money, and handling transactions involving a bank or wallet. That combination makes sense for anyone who already relies on Airtel services and wants fewer separate steps when managing them.
My first impression is that the app is built around quick decisions. You open it because you need to complete something specific, not because you want to browse. That focus is useful when a phone is about to run out of credit or a payment needs attention, although the experience depends heavily on your network connection and on which Airtel services are available to your account.
Developed by Airtel Africa, My Airtel is a free Lifestyle app for everyone. It has reached over 50 million installs and holds a 4.5 average from around 583 thousand ratings, which suggests that it has become a familiar mobile-management option for a large audience. I would still judge it by your own Airtel setup, because an app that is convenient for a prepaid customer may feel less relevant to someone who uses another operator or prefers a dedicated banking application.
How My Airtel feels during real everyday use
Speed expectations when you need a quick recharge
The most important speed test for this app is not how quickly its opening screen appears. It is how little effort it takes to reach the action you need. For a straightforward recharge, the ideal flow is obvious: open the app, choose the relevant mobile service, enter or confirm the amount, and complete the payment. My Airtel is at its best when you already know what you want to do and your account details are ready.
I would not treat it like an offline utility. Recharge and payment actions naturally require a working connection, and the final step may also depend on an external payment or account service. That means a slow mobile signal can make the app feel slow even when the interface itself is responding normally. If you are trying to add credit while travelling, I would start the process before the balance becomes critical rather than waiting until the last possible moment.
A useful habit is to check the selected number and service before confirming. A fast workflow is only helpful if the transaction is directed to the right Airtel line or bill. This is especially important when one person manages several family connections. The convenience of a central app can otherwise become a source of avoidable mistakes if you rush through the confirmation screens.
The app’s broad purpose also means that not every visit will feel equally direct. A mobile recharge is a simple, familiar task. A transfer involving a bank or wallet may require more attention because the destination and amount matter more. I see that as a reasonable trade-off: the app gives you a single starting point, but financial actions deserve a slower final review than buying a small amount of airtime.
What happens during heavier-use moments
My Airtel becomes more valuable when several related tasks happen together. Imagine returning home after work and realizing that your mobile credit is low, a household bill is due, and you want to move money between a wallet and a bank account. Instead of switching between a carrier app, a separate wallet interface, and a banking application, you can begin with the Airtel app and see which of those actions fit your account.
That convenience does not mean every transaction should be bundled into one rushed session. I prefer to complete one payment, check its result, and then start the next. This creates a clearer record in my own mind and makes it easier to notice whether a transaction has finished or is still waiting for a response. When a connection is unstable, repeatedly tapping a payment button is a poor recovery strategy; I would first check the visible status and any account balance change before trying again.
The heavier the session, the more important it becomes to distinguish the app from the underlying service. A screen may load quickly while a payment confirmation takes longer. Conversely, the interface may appear to pause because the network is slow, not because the transaction has failed. I would avoid closing the app immediately during a financial action unless the screen is clearly unresponsive, because restarting too quickly can leave you uncertain about whether the first attempt went through.
For people who use the app only for occasional recharges, this complexity may never matter. For regular users who combine mobile services with money transfers and bill payments, it is worth developing a consistent routine: select the service, verify the destination, confirm the amount, wait for a clear result, and only then move on. That small discipline is one of the best ways to reduce confusion in a multi-purpose payment app.
Reliability and recovering from a disrupted transaction
Reliability here is about more than the app staying open. I want the service to make the state of a transaction understandable, especially when a connection drops. A good recovery process begins with patience. If My Airtel stops responding after you confirm a recharge or transfer, I would not immediately repeat the action. First, I would reconnect if necessary, reopen the relevant account view, and check whether the balance or transaction history reflects the attempt.
This is also where keeping your account information organized helps. If you manage multiple lines or payment destinations, knowing the expected balance before starting gives you something to compare afterward. A simple note of the amount and intended recipient can be useful for larger transfers. These are not glamorous features, but they make a centralised app safer to use in real life.
I find the app more dependable for planned tasks than for emergency improvisation. If I have time to check the connection and confirm the details, the combined workflow is convenient. If I am standing somewhere with weak reception and need an immediate payment result, a familiar alternative such as a direct banking app, a saved USSD process, or a physical payment channel may be more appropriate for that particular moment, depending on what I normally use.
There is another practical limitation: My Airtel is most useful inside the Airtel ecosystem. Someone who changes operators frequently, uses several unrelated financial services, or wants a neutral bill-management tool may find the app less central to daily life. Its strength is not universal coverage of every financial need; it is the ability to connect Airtel-related mobile and money tasks in one place.
Device constraints, storage, and everyday comfort
The stated minimum operating system is Android 8.0, so owners of older phones should check compatibility before planning to depend on it. For supported devices, the more noticeable constraint is likely to be the condition of the phone and connection rather than raw processing power. A crowded device, limited free space, or aggressive background management can make any account app feel less responsive.
I would keep the operating system and the app current when possible. The current version is 1.4.22, and using the available version is sensible for a service that handles account access and payments. I also prefer opening it with enough battery and a stable connection, especially before starting a transfer. That sounds obvious, but it prevents the most frustrating kind of failure: losing power or signal halfway through a task and then having to work out what happened.
On a smaller or older screen, careful reading matters more than visual polish. Payment apps should not be operated by guessing which field is active or which number is selected. If the display is cramped, I slow down and review every confirmation line. The app may be free to install, but the real cost of a mistake can be much higher than the time saved by tapping quickly.
I also would not install it solely because it has a large install base. Popularity tells me that many people find it useful, but it does not replace checking whether your country, Airtel account, preferred payment method, and device all fit the service. The Everyone age rating makes it broadly approachable, yet younger or less experienced users should still have guidance when handling transfers or bill payments.
Where it beats the usual alternatives
The clearest advantage over separate alternatives is consolidation. A carrier-only tool may handle airtime well but leave you to find another route for bills or money movement. A bank app may be stronger for banking details but less convenient for managing Airtel mobile needs. My Airtel sits between those habits, giving Airtel customers one familiar entry point for several common actions.
That does not make it the best tool for every job. A dedicated banking app is often the better choice when I need detailed account management, broader financial information, or services outside the Airtel environment. A wallet app may offer a more focused experience if nearly all my activity is wallet-based. A standard browser or direct service channel can also be preferable when I am using a device where installing another app is impractical.
The trade-off is therefore straightforward: My Airtel reduces app switching, but it also asks me to accept a broader interface. If I only recharge once in a while, that extra scope may feel unnecessary. If I regularly recharge, pay bills, and move money through Airtel-linked services, the wider scope becomes the reason to keep it installed.
Small workflows that make the app more useful
My first practical tip is to separate low-risk and high-attention tasks. I treat a routine recharge as a quick action, but I handle bank or wallet transfers as a review process. Before confirming, I check the destination, amount, and the line or account currently selected. This avoids assuming that the last-used recipient is still the right one.
My second tip is to use the app as a starting point for account awareness, not merely as a button for payments. Before adding credit, I check whether the balance really needs it. Before paying a bill, I confirm the amount shown. This reduces duplicate payments and helps me notice when a previous transaction may still be processing.
My third tip concerns poor connectivity. When the app appears to stall after confirmation, I wait and verify rather than tapping repeatedly. I then check the account or transaction result after reconnecting. If the outcome remains unclear, I switch to a more stable channel for support or confirmation instead of creating multiple attempts. This is particularly important for transfers, where repeating an action can be more serious than waiting.
A fourth useful approach is to keep the app for the services you actually use. If My Airtel is installed only for one occasional task, its value may be limited. But if it replaces several recurring trips through different apps, the saved attention is meaningful. I would organise my routine around the app’s strongest role—Airtel mobile and connected payment tasks—rather than expecting it to replace every financial tool on my phone.
Who should use it and who should skip it
I recommend My Airtel to Airtel customers who want a single place for mobile recharges, bill payments, and money transfers involving a bank or wallet. It is especially suitable for people who manage more than one Airtel-related responsibility, such as a personal line plus household services. The free price also makes trying it low-risk from an installation standpoint.
I would be more cautious if your phone runs an older operating system, your connection is frequently unreliable, or you rarely use Airtel services. In those cases, a lighter, more specialised option may fit your routine better. Someone who needs advanced banking tools should not choose this app simply because it includes money transfer functions; the right comparison is with the banking service they trust and use most often.
The large user base and strong average rating give me confidence that this is not an obscure experiment, but they do not erase the practical limitations of a service-dependent app. Your experience can change with network conditions, account type, device age, and the exact transaction you are attempting. I would install it when Airtel is already central to my mobile life, not as a general-purpose replacement for all payment apps.
My performance verdict after using it as a daily utility
My Airtel feels most effective when I approach it with a clear task and a stable connection. It can shorten the path from “I need to recharge or pay something” to a completed action, and its ability to bring mobile, bill, bank, and wallet-related activities together is genuinely useful. The app’s perceived speed is strongest in simple workflows; more involved transactions naturally require more checking and may feel slower when external services are involved.
Its resource demands are not the main reason I would hesitate. The bigger concerns are device compatibility, connection quality, and the need to recover carefully when a transaction does not immediately show a result. Those are manageable if I avoid repeated taps, verify balances, and keep an alternative channel available for urgent situations.
Overall, I see My Airtel as a practical companion for Airtel users rather than a universal finance app. It earns a place on my phone when consolidation matters and when I regularly use the services it brings together. If your priority is fewer app switches without losing control of each payment, My Airtel is worth considering. If you need specialist banking features, operator-neutral tools, or dependable offline access, I would choose a more focused alternative instead.
With its release on August 28, 2019 and its current version 1.4.22, the app has had time to establish itself as part of Airtel’s wider mobile experience. My final view is positive but practical: use it for the Airtel tasks it handles well, slow down for transfers and bills, and judge its value by how often it replaces separate routines in your own day.
Gallery
My Airtel Pros and Cons
- Quick access to Airtel account and service details
- Convenient mobile recharge and bill payment options
- Data balance and plan validity are easy to monitor
- Supports multiple Airtel services in one application
- Digital payment options make transactions more convenient
- Some features may vary depending on your country or Airtel region
- App performance can depend heavily on network quality
- Promotional notifications may become frequent
- Certain support requests may still require contacting customer care
- Updates or maintenance can temporarily affect account access
My Airtel Frequently Asked Questions
What is My Airtel and what can I do with it?
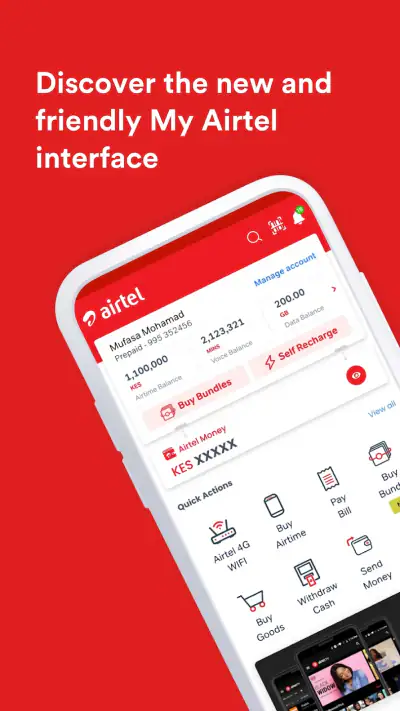
My Airtel is the official self-service app for Airtel customers, although the exact features can vary by country and Airtel network. After signing in with your Airtel number, you can usually check your balance, monitor data usage, recharge prepaid services, pay postpaid bills, manage plans, and view available offers. Some versions also provide account support, transaction history, and access to additional Airtel services.
Is My Airtel free to download and use?
The My Airtel app is generally free to download from Google Play or the Apple App Store, and Airtel normally does not charge a separate fee simply for opening or using the application. However, mobile data charges may apply if you use the app without Wi-Fi, depending on your plan. Payments, recharges, subscriptions, or selected third-party services made through the app can also involve their own charges.
Can I recharge my Airtel number or pay bills through the app?
Yes, one of the main purposes of My Airtel is to simplify account payments. Prepaid users can typically purchase recharge vouchers or data packages, while postpaid customers may be able to view and settle their bills directly in the app. Available payment methods differ by region and may include bank cards, mobile wallets, online banking, or other local options. Always review the amount and recipient number before confirming.
Is My Airtel safe for managing my account and making payments?
My Airtel is the official Airtel customer application, so it is generally safer than using unofficial recharge or account-management tools. The app may require your phone number, verification code, and payment information to provide its services. Download it only from an official app store, check that the developer is Airtel, keep your operating system updated, and never share one-time passwords or account credentials with anyone.
Why cannot I log in or see my Airtel balance in the app?
Login and balance problems can result from several causes, including an incorrect phone number, an expired verification code, weak internet access, an outdated app version, or temporary Airtel maintenance. Confirm that you selected the correct country or Airtel region, then restart the app and request a new code. If the issue continues, clear the app cache or reinstall it, and contact Airtel support through the official website or customer-care channels.














